Up to €548.91
Savings of our Wealth clients due to tax optimisation
Save up to €560¹ yearly – without any effort.
Complex taxes made simple
Automatic and free of charge for all wealth portfolios
Return optimisation through optimum tax efficiency
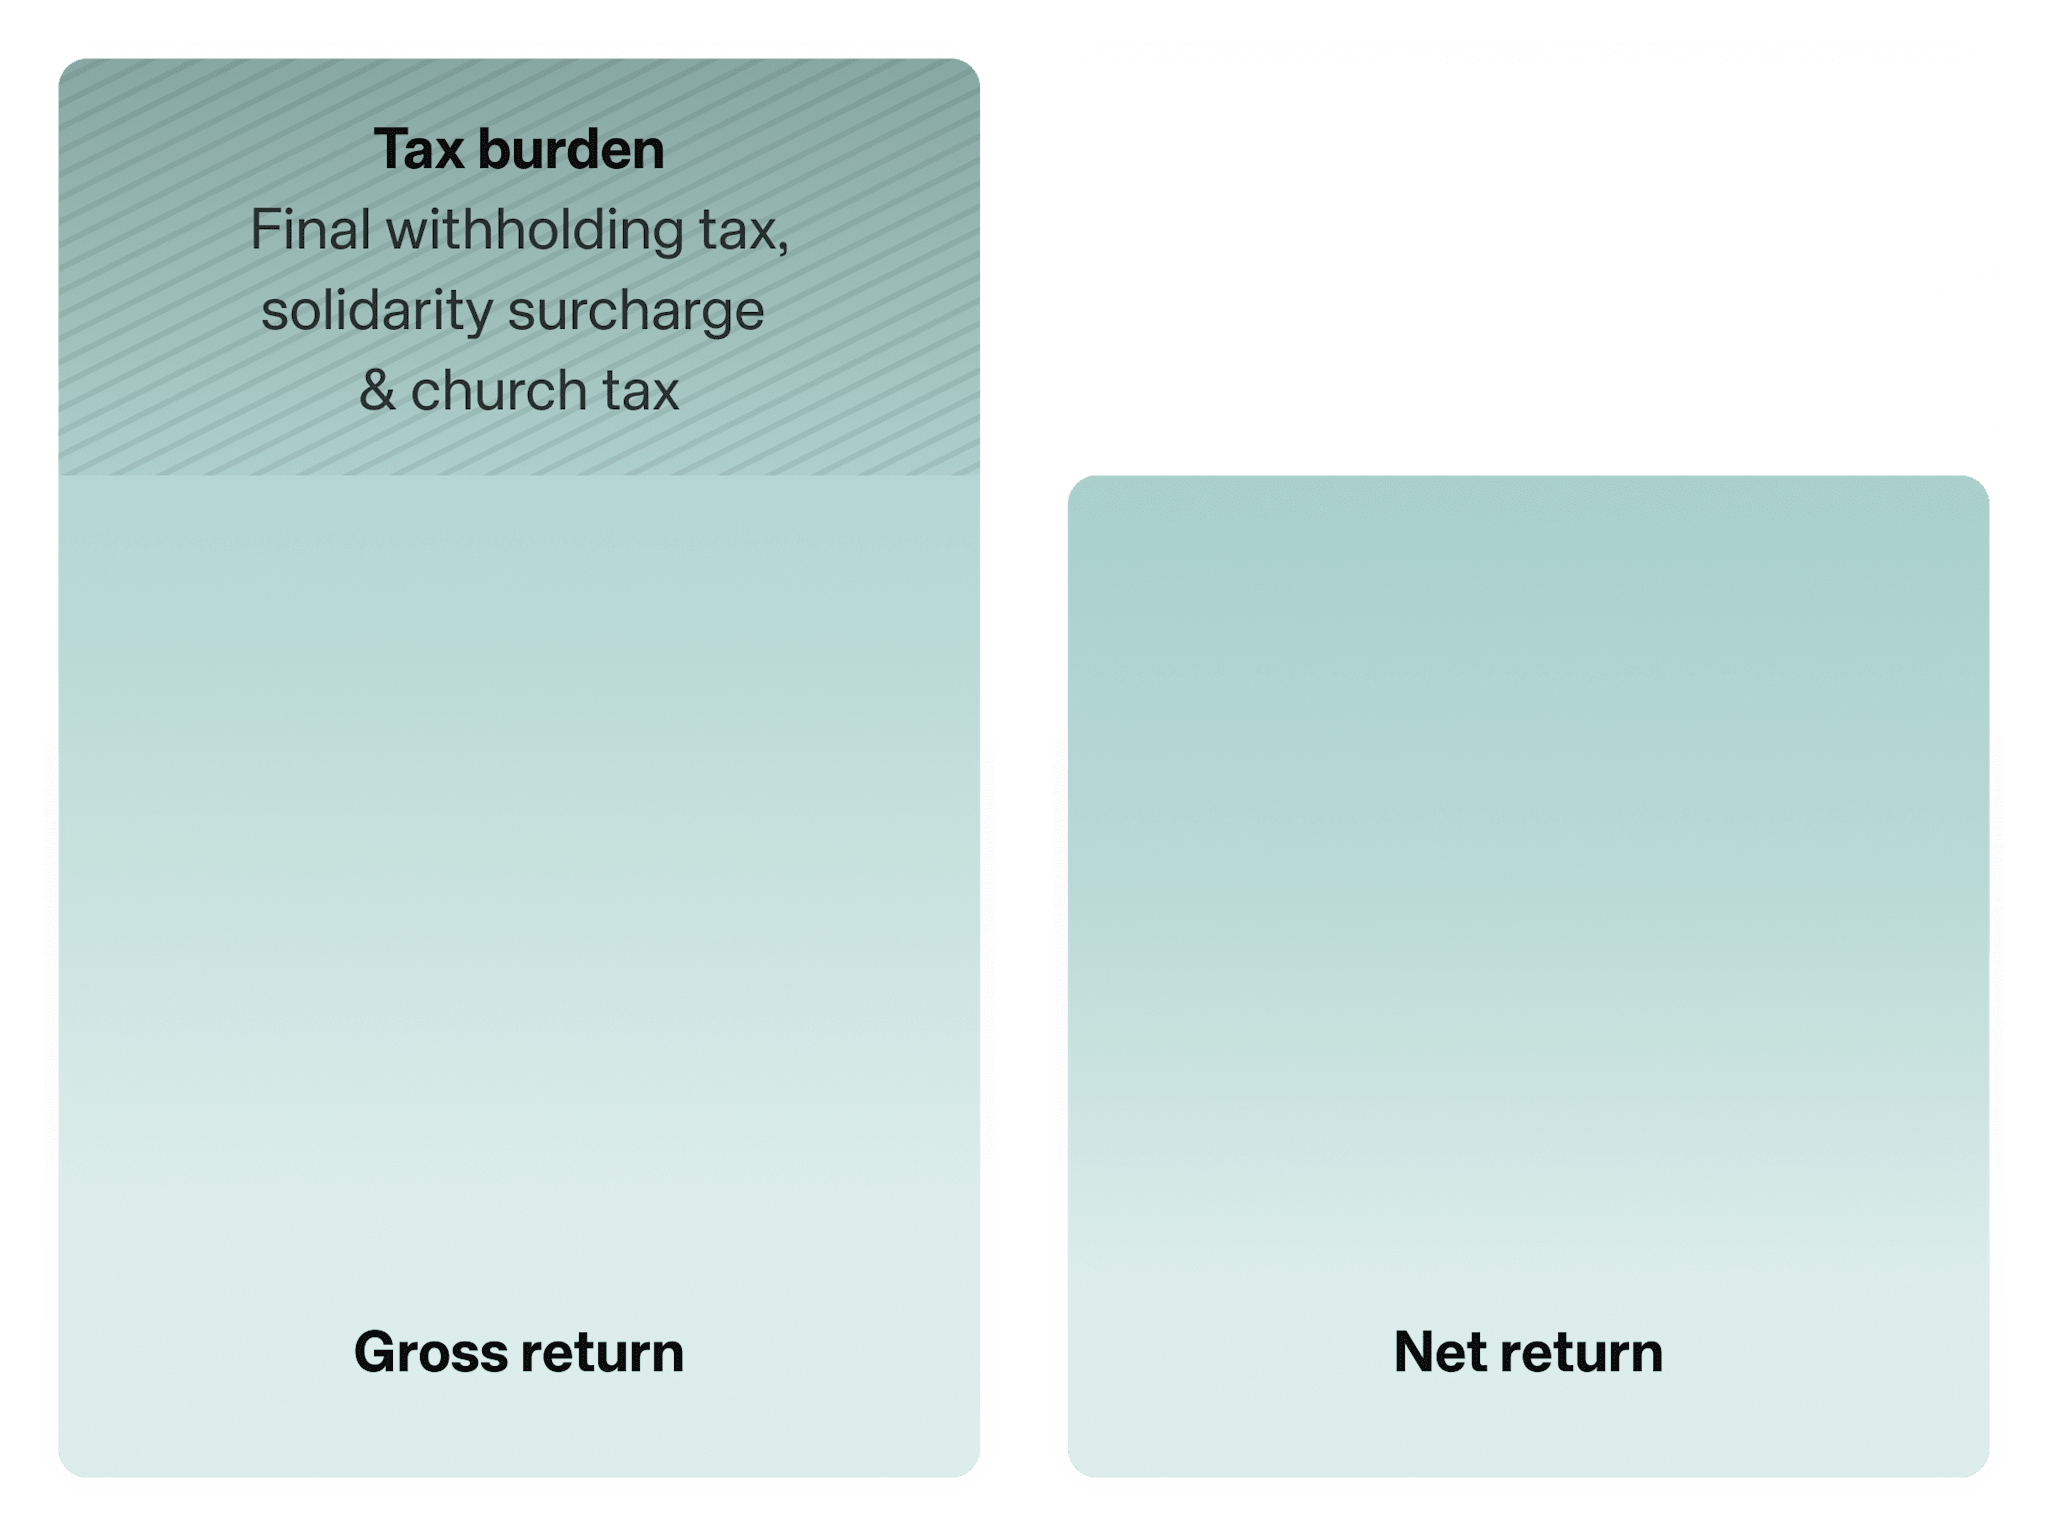
Anyone who is liable for tax in Germany and invests in shares or ETFs must pay withholding tax on capital gains. Capital gains arise, for example, from distributions or the sale of ETFs at a profit. The tax due on this is withheld directly by the custodian bank upon sale and thus reduces the return. Once tax has been withheld, it is no longer available as funds for further investments, which reduces the compound interest effect. For this reason, tax aspects are essential, especially for long-term investments.
The flat-rate withholding tax amounts to 25 per cent of the taxable profit. The solidarity surcharge and, if applicable, church tax are added to this. The maximum tax burden thus rises to just under 28 per cent. In addition to the final withholding tax, some products are subject to withholding tax or double taxation agreements.
Optimal utilisation of the exemption order
Consideration of individual tax characteristics of the investor
Selection of tax-favourable ETFs
Savings of our Wealth clients due to tax optimisation
Wealth clients with an exemption order in place that benefited from tax optimisation.
of the Wealth portfolios had tax savings exceeding the management fees for wealth management, thereby offsetting these.
Status: June 2025
Save up to €560²
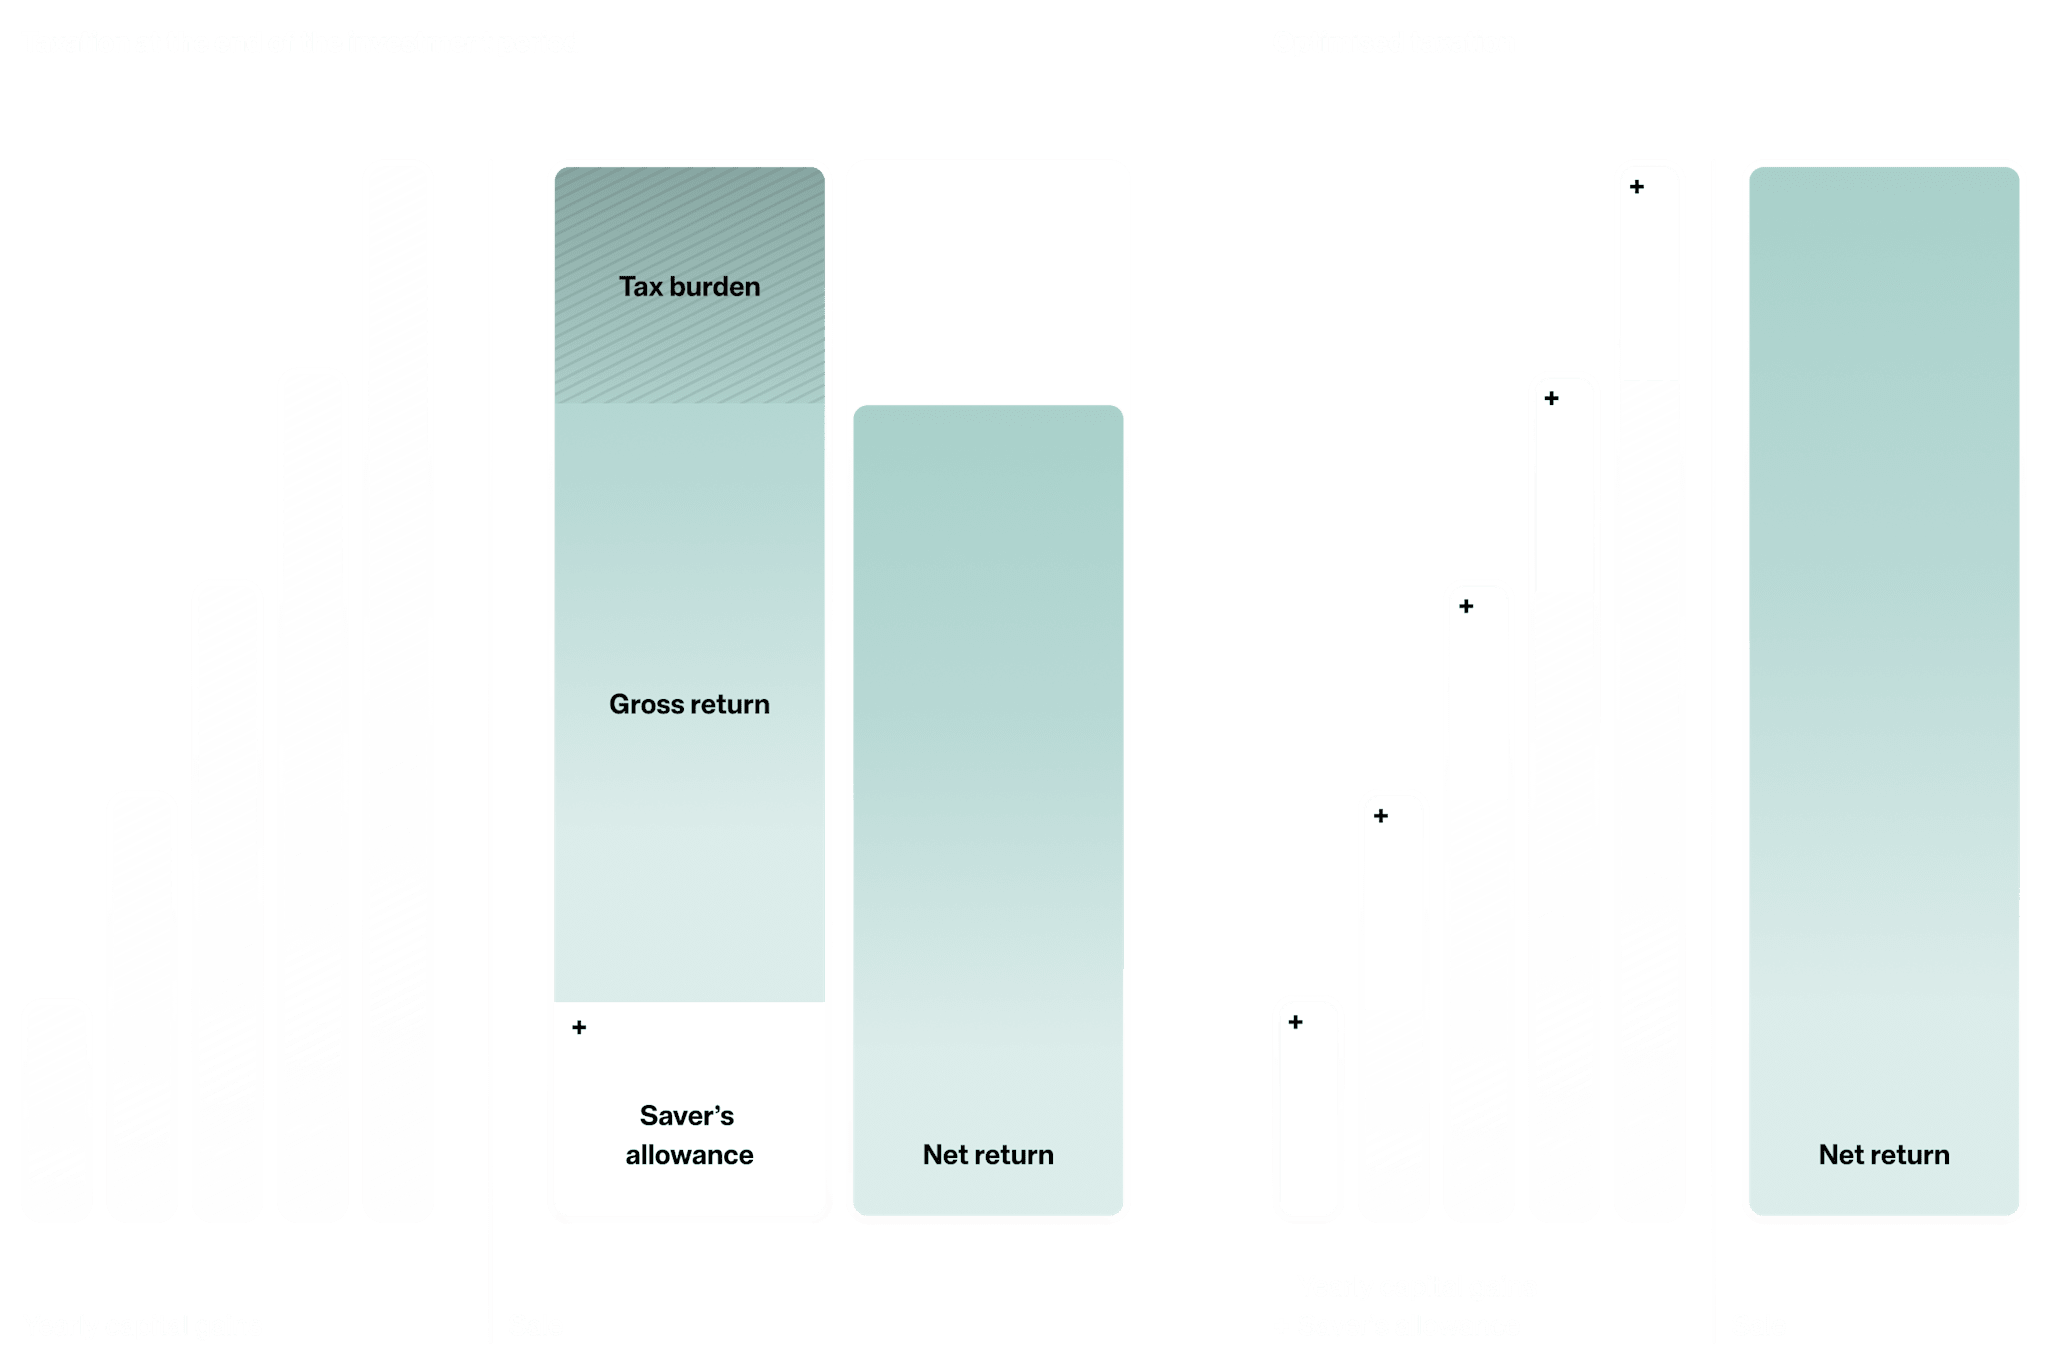
The use of the exemption order makes it possible not to have to pay tax on capital income up to a certain amount each year. If an exemption order has been issued, the custodian bank will not deduct the withholding tax on capital income that would otherwise be due until the exemption order sum is reached. This means that there is no unnecessary tax burden.
To make optimal use of the exemption order, we analyse all portfolios towards the end of the tax year. If an exemption order has not yet been fully utilised, we sell ETFs accordingly and thus realise capital gains. We reinvest the proceeds from the sale promptly. In this way, we make the portfolios more favourable from a tax perspective than if all income was only taxed at the end of the investment period.
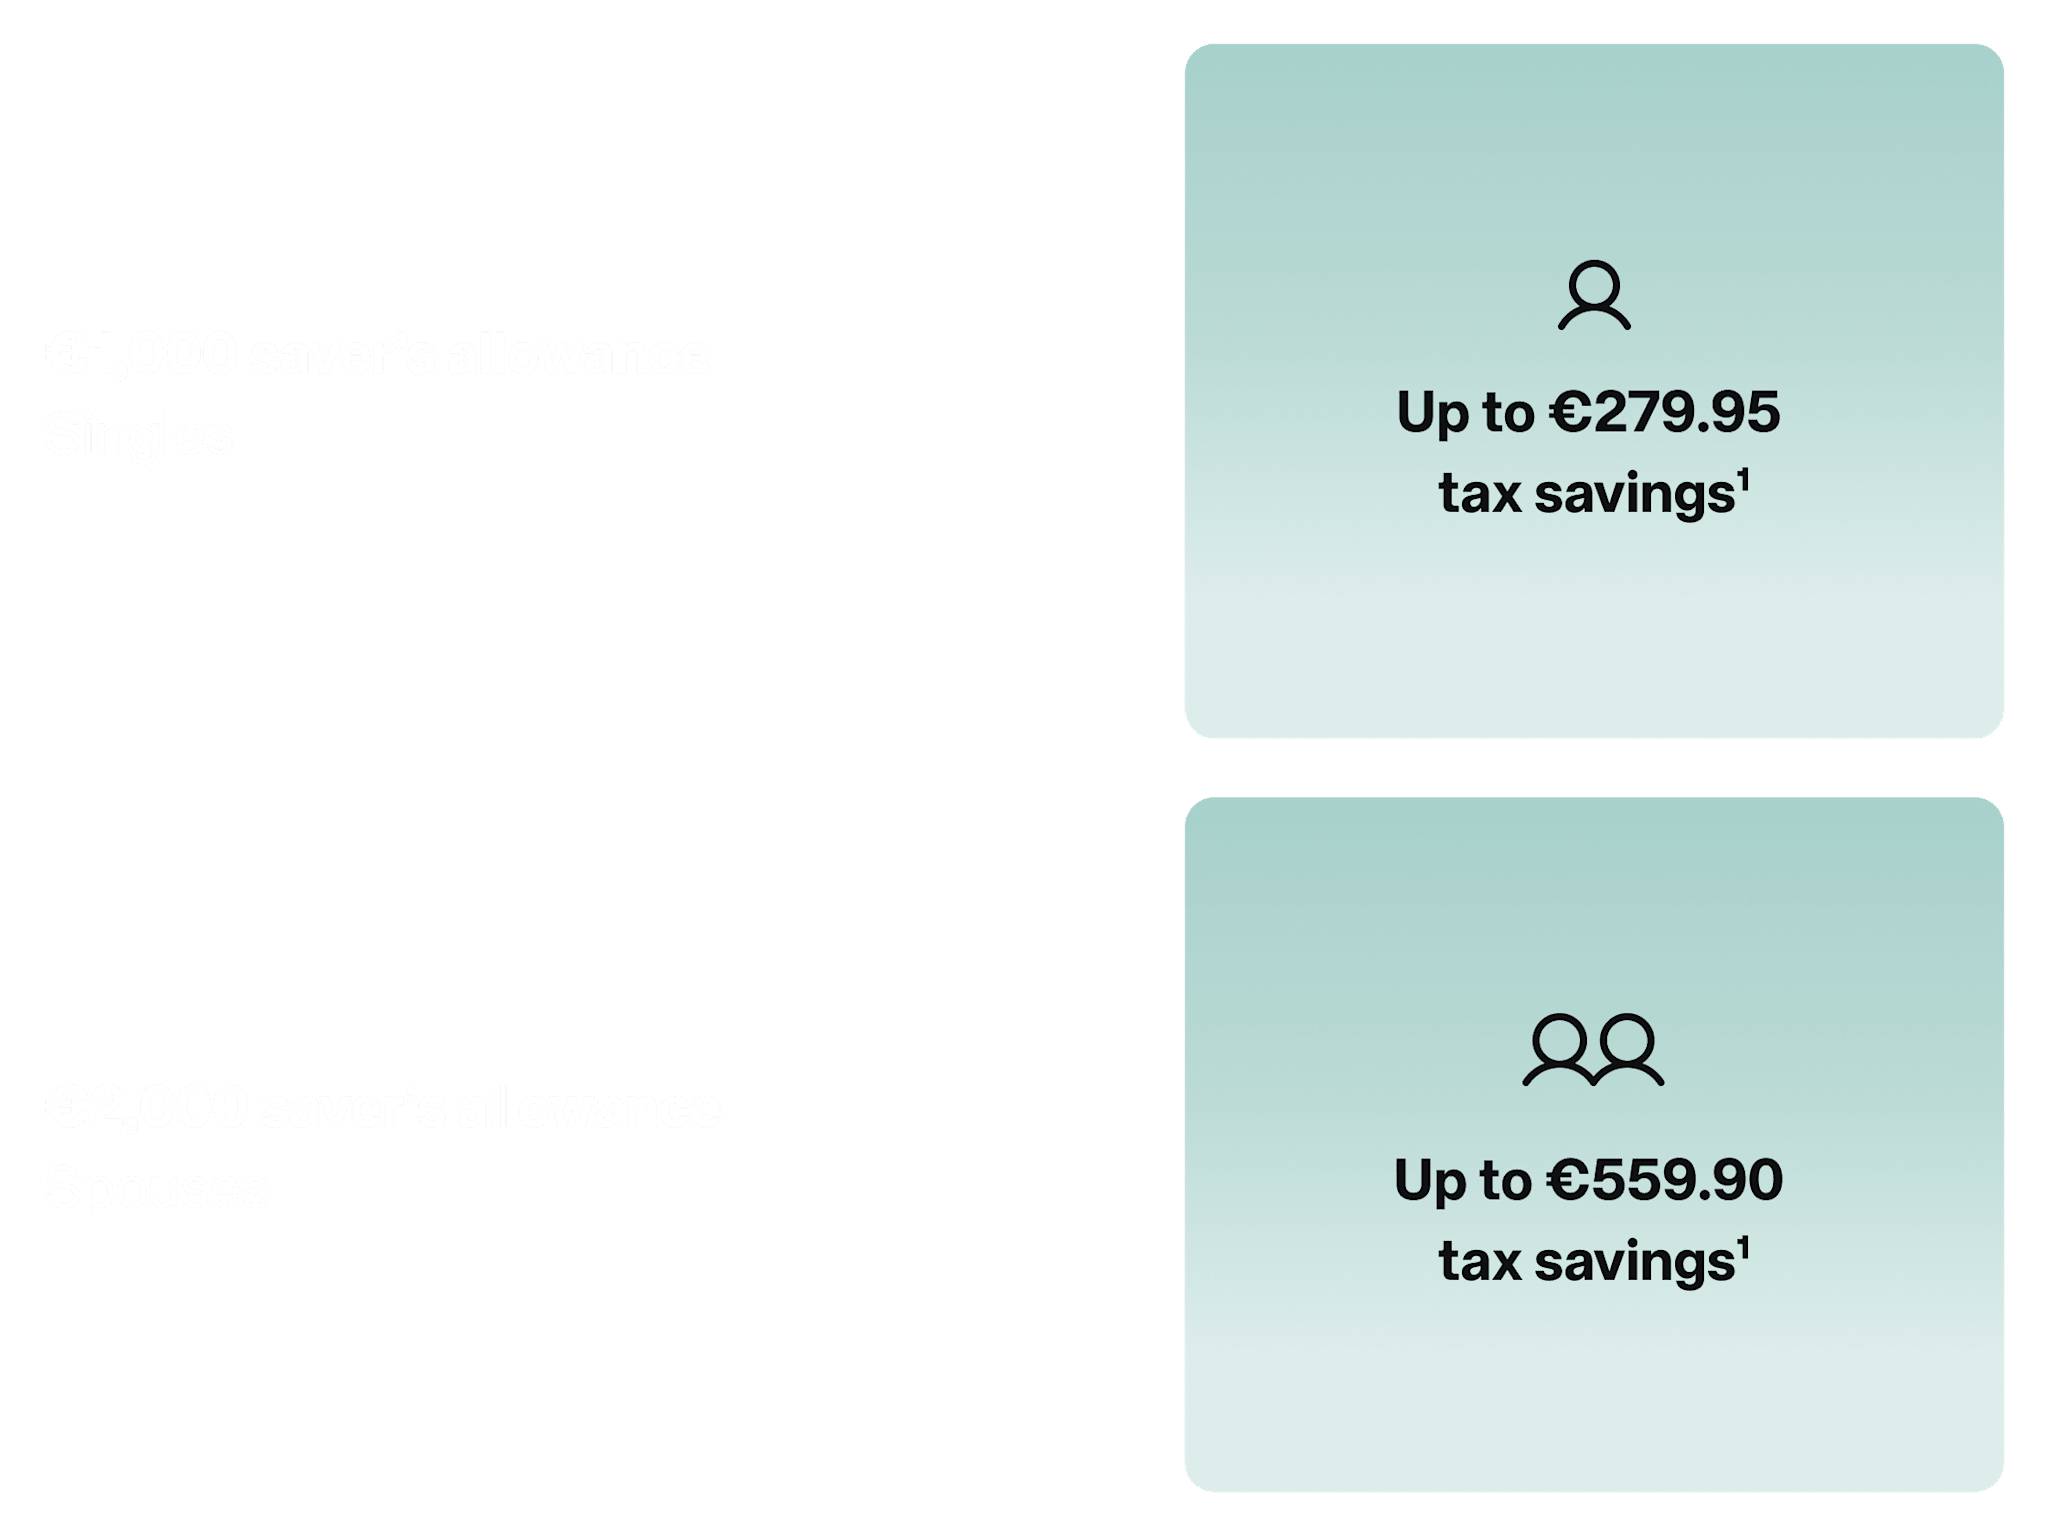
Our investment technology takes the following into account:
Transaction history for determining capital gains
Outstanding distributions (if applicable)
Other client portfolios (if available)
For each portfolio, we optimise the ratio between the potential tax savings and the transaction costs resulting from the bid-ask spread.
All investors have a different tax burden. In order to optimise this to the maximum, we look at each client individually:
Exact tax rate
Size of the portfolio
Amount of the exemption order and individual or joint assessment
Existing loss pots
We estimate the tax effect of transactions on the basis of these characteristics. The withholding tax retained by the custodian bank reduces the liquidity available for immediately subsequent purchase transactions, for example in the case of rebalancing. Our tax estimate ensures that the necessary liquidity is available for same-day rebalancing in the portfolios.
ETFs have different tax characteristics. The right choice of these products can contribute to tax optimisation. We consider the following aspects, among others:
Tax domicile & replication method
Depending on the domicile of the ETF and the geographical focus of the replicated index, there are different tax burdens at fund level due to withholding tax and existing double taxation agreements. We then prefer ETFs with a domicile that is favourable for our clients. For example, the 30% withholding tax can be reduced to 15% with a physical ETF launched in Ireland.
We also use so-called synthetic ETFs in some portfolios. One advantage of this is that, by law, they do not have to pay US withholding tax on dividends. One example of this is the S&P 500 Index: the iShares S&P 500 Swap ETF contained in the World Portfolio Classic, BIP Global and Allweather Portfolio is therefore not subject to withholding tax. It does not matter where the fund is domiciled.
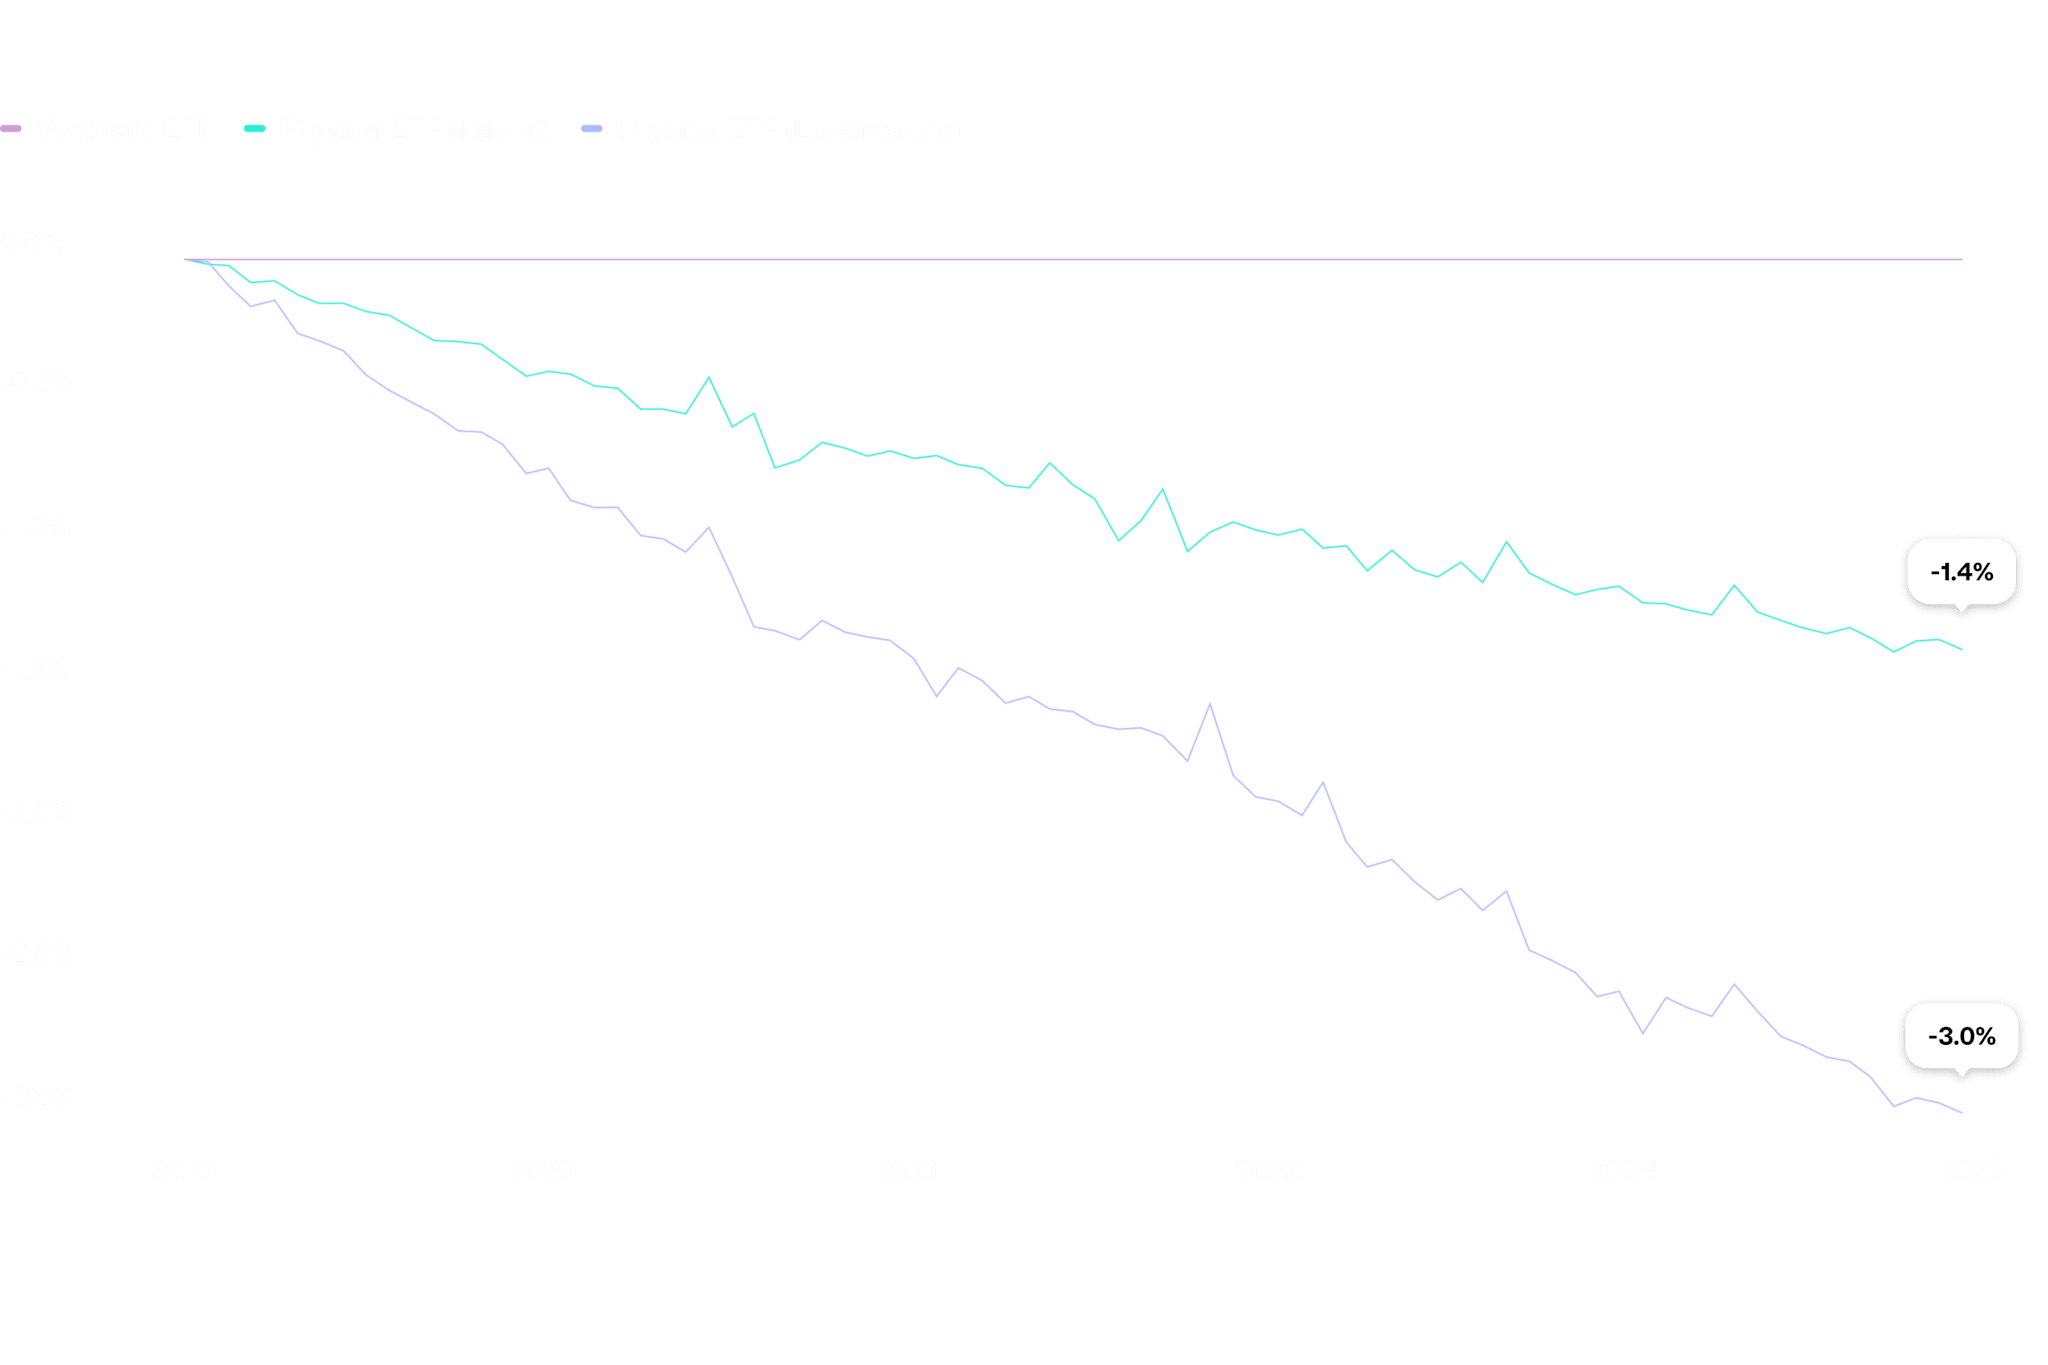
Source: Bloomberg
Accumulating ETFs are taxed at a flat rate by means of an annual advance lump sum. This is based on the base rate of the Bundesbank (long-term achievable yield on public bonds) and is also limited to the increase in value of the ETF in the calendar year. As public bonds have lower yields compared to other asset classes (e.g. stocks or corporate bonds) and income is only taxed at all in years with an increase in value, part of the tax burden for current income is shifted to the future. Compared to "distributors", more capital remains in the ETF with "accumulators" and can work for you.
Certain domestic income is already taxed in the ETF. In order to avoid double taxation, part of the income is exempt from taxation at custody account level (partial exemption). The partial exemption rate depends on quotas for certain asset classes in the ETF. The partial exemption for investors therefore varies depending on the asset class and weighting in the ETF.
In order to optimise in the best possible way, we check which products in a portfolio are affected, which charges would be incurred and how high these are in relation to the portfolio. Based on this, we ensure that we create sufficient liquidity for the relevant point in time.
Answers to further frequently asked questions are answered in our Help Center.
¹ Calculation assuming an exemption order of €2,000, capital gains tax of 25%, solidarity surcharge of 5.5% and church tax of 9%.
Note: Scalable Capital does not provide tax advice. The tax treatment depends on individual circumstances and may change in the future.